SHL Numerical Reasoning Test (2026): Format, Scoring, Practice & Strategy
SHL Numerical Reasoning Test practice should train more than arithmetic. It should teach you how to read the question, select the correct data, choose the shortest reliable calculation and avoid the distractor created by a wrong base, row, unit or percentage.
This guide combines 8 original SHL-style numerical reasoning practice questions with worked answers, chart interpretation, percentage and ratio formulas, current SHL assessment-format guidance, calculator strategy, time management and the ReasoningCampus six-step solving method. It is designed for candidates preparing for SHL Numerical Reasoning, Verify Interactive numerical assessments, Verify G+ / General Ability contexts, graduate schemes, internships, finance, consulting, analyst, engineering and other pre-employment numerical aptitude tests.
What the SHL Numerical Reasoning Test Measures
SHL numerical assessments are designed to test how accurately you can interpret numerical or statistical information and make a correct decision or inference from it. The emphasis is not advanced mathematics; it is understanding data in a realistic work context and choosing the correct conclusion under time pressure.
In practice, candidates may need to read tables, bar charts, line graphs, pie charts, targets, costs, revenues, percentages and other business data. The difficult part is often deciding which figures matter before calculating anything.
Data interpretation
Identify the right row, column, period, axis, legend, unit and comparison before you calculate.
Numerical judgement
Decide whether the task requires a percentage, ratio, reverse total, average, margin, growth rate or another relationship.
Decision under time pressure
Calculate exactly when necessary, estimate when it is safe and eliminate answers that cannot fit the data.
Current SHL Numerical Test Formats Candidates May Encounter
Do not assume that every employer uses the same numerical assessment. SHL has multiple current assessment families, and older Verify products have changed over time. Your invitation, test title and instruction screen are the best guide to the format you will actually take.
| Assessment context | What to expect | Preparation priority |
|---|---|---|
| Verify Interactive – Numerical Reasoning | Interactive, workplace-relevant numerical tasks. SHL lists it as the replacement path for the legacy Verify Numerical Reasoning product. | Understand the interface as well as the calculation; practise charts, graphs and business data. |
| Verify Interactive G+ | General cognitive ability context covering numerical, deductive and inductive reasoning. | Switch efficiently between calculation, rule application and pattern recognition. |
| Other SHL numerical / calculation assessments | The exact test, timing, navigation and calculator rules depend on the assessment selected by the employer. | Read the invitation and on-screen instructions before applying any generic timing strategy. |
Numerical Reasoning Question Types and Common Traps
Strong preparation covers the numerical relationships that appear repeatedly in recruitment tests, but it also trains the error pattern attached to each relationship. The same arithmetic can become much harder when it is hidden inside a chart or a multi-step business rule.
| Question type | What it tests | Typical trap |
|---|---|---|
| Tables | Rows, columns, totals and periods | Wrong row, year or unit |
| Bar charts | Comparison of categories | Misreading the scale |
| Line graphs | Change and trends over time | Using the wrong period |
| Pie charts | Part-to-whole reasoning | Using a percentage without finding the total |
| Mixed / combo charts | Combining more than one data source | Ignoring one rule or series |
| Percentages | Percentage of, increase and decrease | Wrong base value |
| Reverse percentages | Recovering an original value | Subtracting instead of dividing |
| Ratios and proportions | Comparing and scaling quantities | Reversing the ratio or using the wrong whole |
| Averages | Mean values | Wrong number of items |
| Weighted averages | Groups of unequal size | Averaging averages directly |
| Currency conversion | Exchange-rate direction | Multiplying when you should divide |
| Profit, cost and revenue | Business arithmetic | Confusing profit with revenue |
| Profit margin | Profit as a share of revenue | Dividing by cost |
| Growth and CAGR | Relative and compound change | Treating compound growth as simple growth |
| Data sufficiency | What can actually be concluded | Adding unsupported assumptions |
| Business KPIs | Productivity, conversion and efficiency | Wrong denominator |
| Inventory | Opening stock, usage and closing stock | Ignoring one stock movement |
| Estimation | Fast approximate selection | Overcalculating when options are far apart |
The ReasoningCampus 6-Step Solving Method
At ReasoningCampus we use one repeatable six-step sequence so that the candidate does not start typing numbers into a calculator before understanding the task.
Read the target first
Decide whether the question asks for a number, percentage, ratio, difference, trend, highest value or supported conclusion.
Locate only relevant data
Check row, column, month, year, unit, currency, chart scale, legend and any note that changes the calculation.
Check the answer, not just the arithmetic
Confirm the denominator, unit, direction of change and whether you answered the exact wording of the question.
Calculation principle: use the shortest reliable calculation. If answer options are widely separated, estimation may be enough. If the options are close, calculate precisely and avoid rounding too early.
Numerical Reasoning Formulas You Need for the Test
You do not need advanced mathematics, but you do need the core relationships to be automatic enough that your attention can stay on the data.
Value × percentagePart ÷ total × 100(New − old) ÷ old × 100(Old − new) ÷ old × 100Final value ÷ final multiplierTotal ÷ number of itemsΣ(value × weight) ÷ ΣweightsRevenue − costProfit ÷ revenue × 100Output ÷ inputFollow the direction in which the rate is quoted(Final ÷ initial)^(1 ÷ years) − 18 SHL Numerical Reasoning Practice Questions with Worked Answers
Use these worked examples to practise choosing the correct data, percentage base and calculation. This guided set also appears in our mixed practice bank; for fresh questions, try the eight separate numerical worked examples. They progress through grouped bars, stacked data, a line chart, pie charts, actual-versus-target comparisons, thresholds and reverse percentages. Try each question before opening the solution.
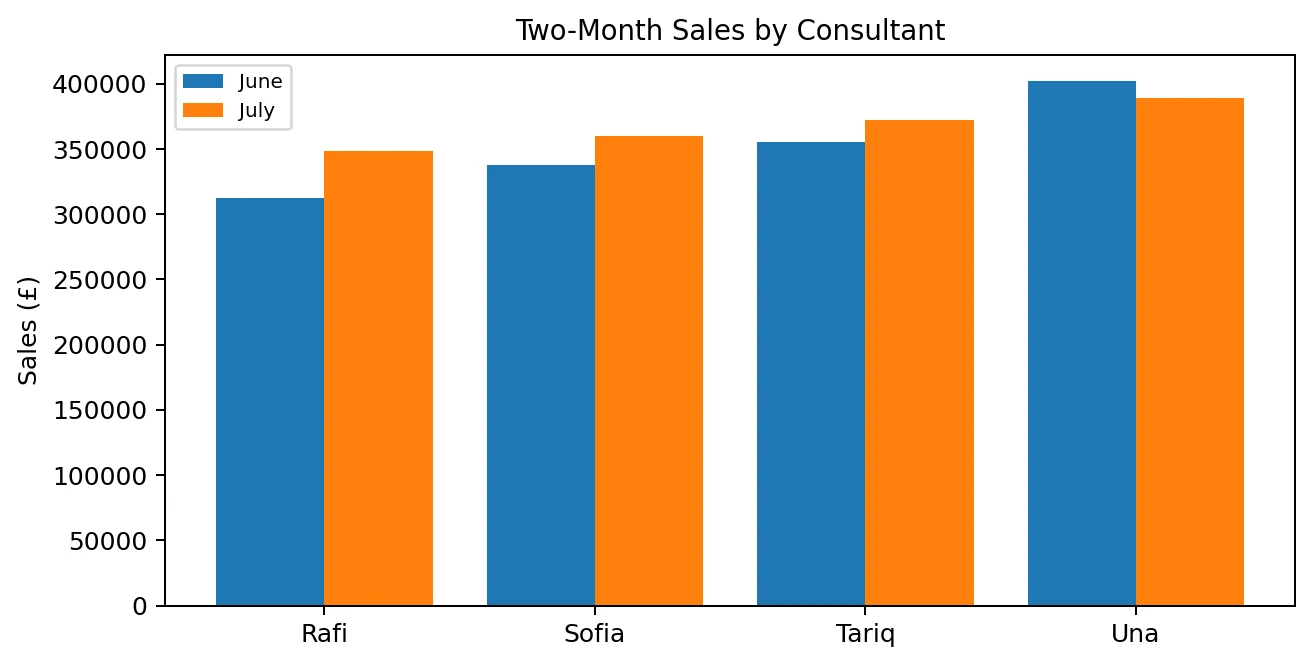
| Rules / Notes | |
|---|---|
| Base salary per month | £2,100 |
| Commission rate | 2.4% of combined net sales |
| July adjustment | 3% of July sales are returned before commission |
| Bonus | £500 if combined net sales exceed £700,000 |
Question. What were Tariq's total earnings across June and July, rounded to the nearest pound?
| Tariq’s sales | Amount |
|---|---|
| June | £355,000 |
| July, before returns | £372,000 |
View answer & worked solution
- This question is a trap because the commission is based on combined net sales over two months, not on one month in isolation.
- Tariq's June sales were £355,000 and July sales were £372,000.
- July sales are reduced by 3% returns before commission, so July net sales = £372,000 × 0.97 = £360,840.
- Combined net sales = June £355,000 + July net £360,840 = £715,840.
- Commission = 2.4% of combined net sales = £715,840 × 0.024 = £17,180.16.
- The consultant receives two months of base salary: 2 × £2,100 = £4,200.
- Because combined net sales exceed £700,000, the fixed bonus of £500 is added.
- Total earnings over the two months = £4,200 + £17,180.16 + £500 = £21,880.16, which rounds to £21,880 to the nearest pound.

| Rules / Notes | |
|---|---|
| Adjusted pay includes | Base salary + commission + bonus only |
| Bonus cap for this question | Any bonus above £500 counts as £500 |
| Travel allowance | Ignore it for this question |
Question. Who had the highest adjusted pay under these rules?
| Employee | Base salary | Commission | Bonus |
|---|---|---|---|
| Quinn | £2,550 | £2,200 | £450 |
| Rosa | £2,550 | £2,050 | £600 |
| Stefan | £2,550 | £1,900 | £750 |
| Talia | £2,550 | £2,300 | £500 |
View answer & worked solution
- The trap is that the chart shows four components, but the question asks for adjusted pay under a special rule.
- Adjusted pay includes base salary, commission and bonus only. Travel allowance is ignored, and any bonus above £500 is capped at £500.
- Quinn: adjusted pay = £2,550 + £2,200 + min(£450, £500) = £5,200.
- Rosa: adjusted pay = £2,550 + £2,050 + min(£600, £500) = £5,100.
- Stefan: adjusted pay = £2,550 + £1,900 + min(£750, £500) = £4,950.
- Talia: adjusted pay = £2,550 + £2,300 + min(£500, £500) = £5,350.
- The highest adjusted pay is £5,350, so the correct answer is Talia.
| Rules / Notes | |
|---|---|
| Commission rate | 3% of sales |
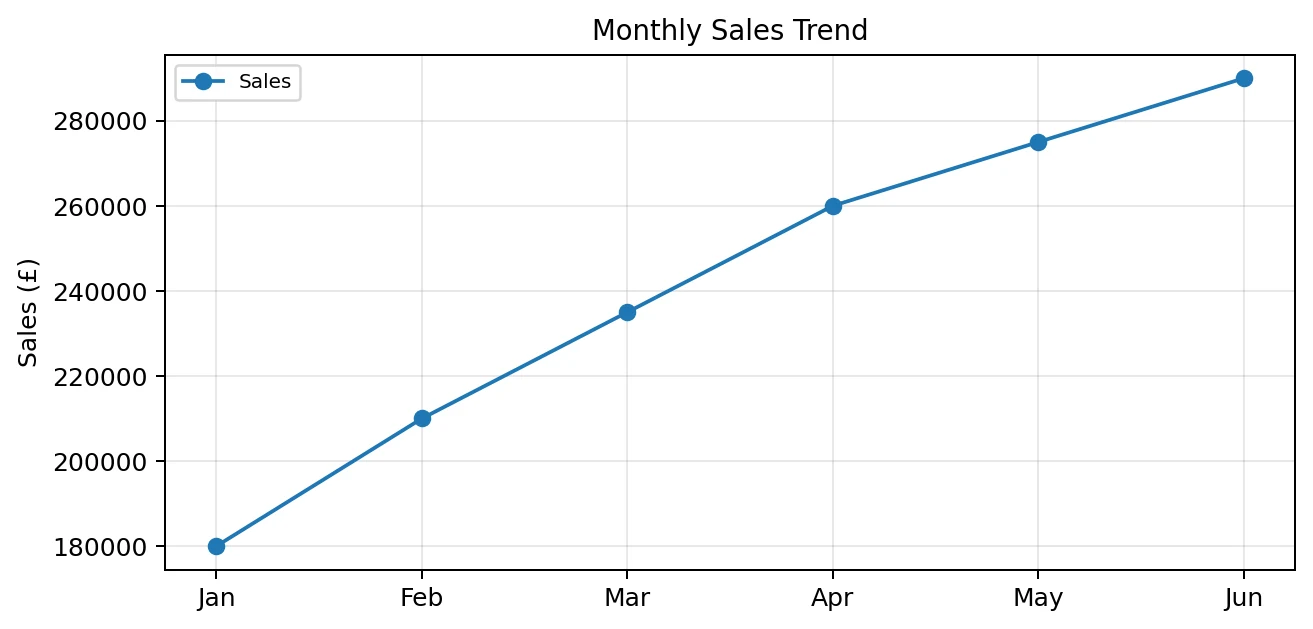
Question. What commission was earned on Quarter 2 sales?
| Month | Sales |
|---|---|
| January | £180,000 |
| February | £210,000 |
| March | £235,000 |
| April | £260,000 |
| May | £275,000 |
| June | £290,000 |
View answer & worked solution
- Quarter 2 includes April, May and June.
- Read the chart: April = £260,000, May = £275,000, June = £290,000.
- Total Q2 sales = £260,000 + £275,000 + £290,000 = £825,000.
- Commission is 3% of Q2 sales, so commission = £825,000 × 0.03 = £24,750.
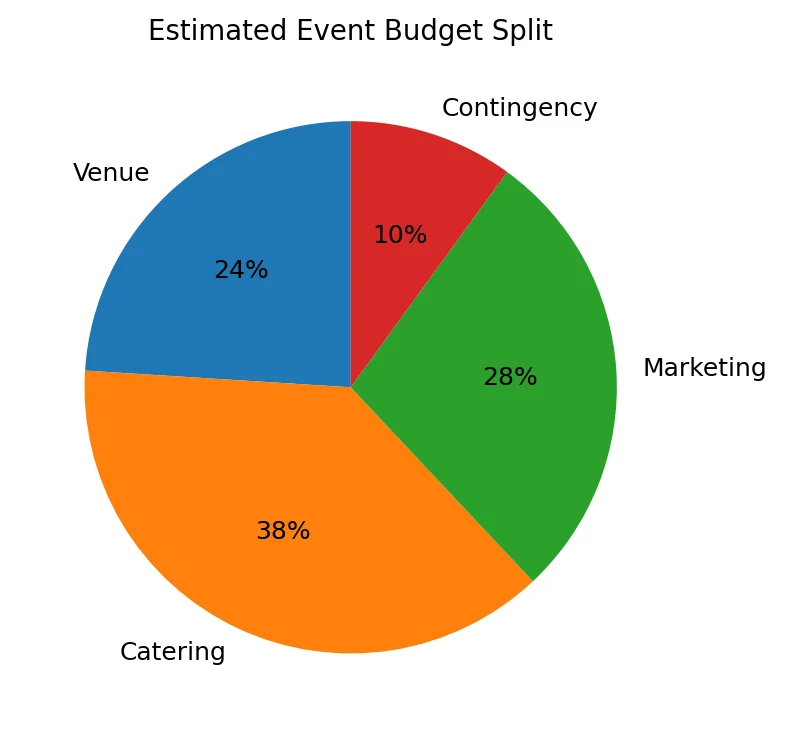
Question. If the Venue slice equals £4,800, what is the total event budget?
| Category | Share |
|---|---|
| Venue | 24% |
| Catering | 38% |
| Marketing | 28% |
| Contingency | 10% |
View answer & worked solution
- Read the pie chart first. Venue represents 24% of the total budget.
- If 24% equals £4,800, then the whole budget equals £4,800 ÷ 0.24.
- Total budget = £20,000.
| Rules / Notes | |
|---|---|
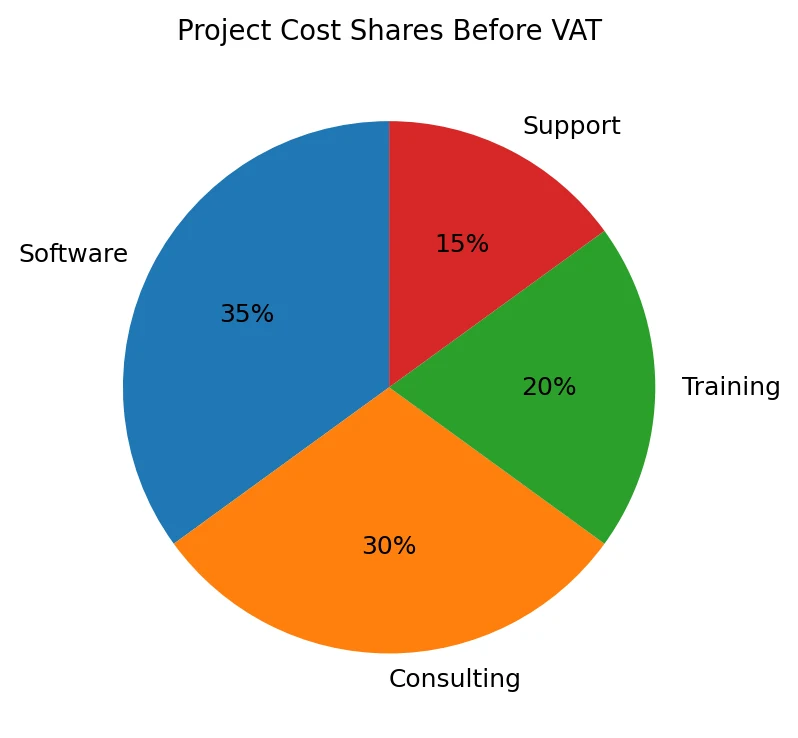
| Administration fee | 4% of the pre-VAT total |
| VAT | 20% added after the fee |
Question. If the Training slice equals £7,600, what is the final gross project cost?
| Category | Share before fee and VAT |
|---|---|
| Software | 35% |
| Consulting | 30% |
| Training | 20% |
| Support | 15% |
View answer & worked solution
- The pie chart gives the split of the pre-VAT project cost.
- Training is 20% of the pre-VAT total. If Training costs £7,600, then the pre-VAT total is £7,600 ÷ 0.20 = £38,000.
- An administration fee of 4% is then added: £38,000 × 0.04 = £1,520.
- Pre-VAT total after the fee = £38,000 + £1,520 = £39,520.
- Finally add 20% VAT: £39,520 × 1.20 = £47,424.00.
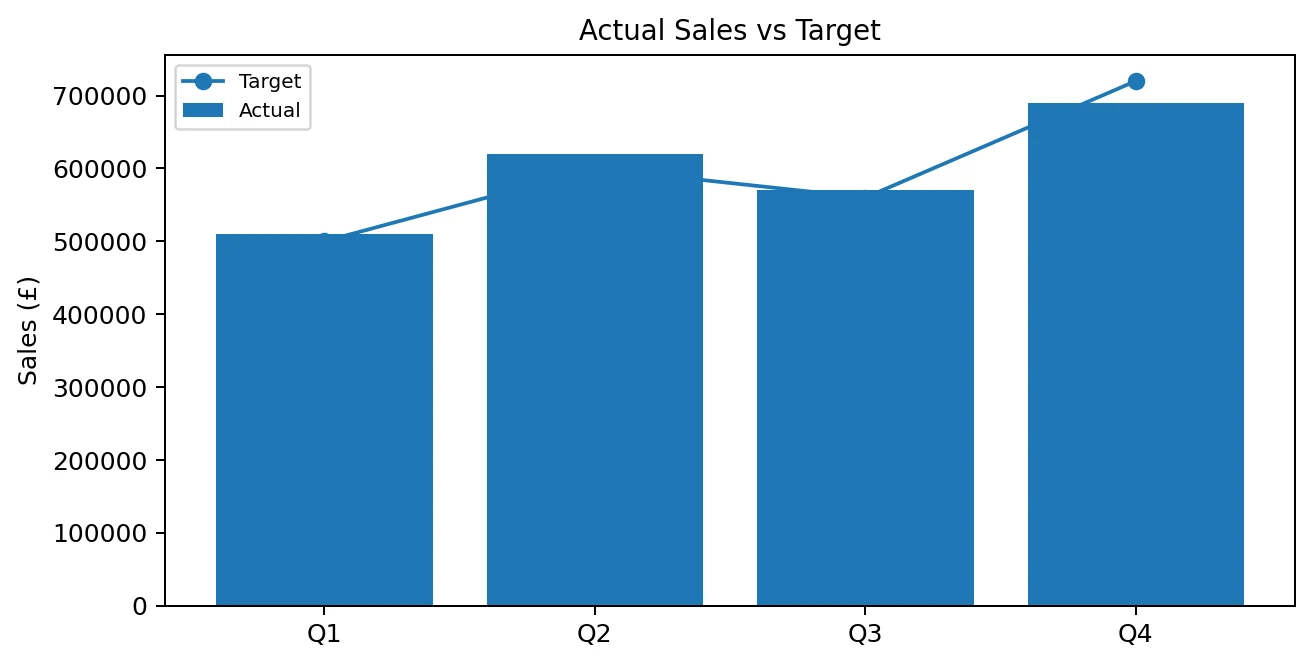
Question. In which quarter did actual sales exceed target by the largest proportion?
| Quarter | Actual sales | Target |
|---|---|---|
| Q1 | £510,000 | £500,000 |
| Q2 | £620,000 | £600,000 |
| Q3 | £570,000 | £560,000 |
| Q4 | £690,000 | £720,000 |
View answer & worked solution
- Proportional over-performance means excess divided by target, not just the raw difference.
- Q1: (£510,000 - £500,000) ÷ £500,000 = 2.0%.
- Q2: (£620,000 - £600,000) ÷ £600,000 = 3.3%.
- Q3: (£570,000 - £560,000) ÷ £560,000 = 1.8%.
- Q4: (£690,000 - £720,000) ÷ £720,000 = -4.2%.
- The largest positive proportion is 3.3%, so the answer is Q2.
| Rules / Notes | |
|---|---|
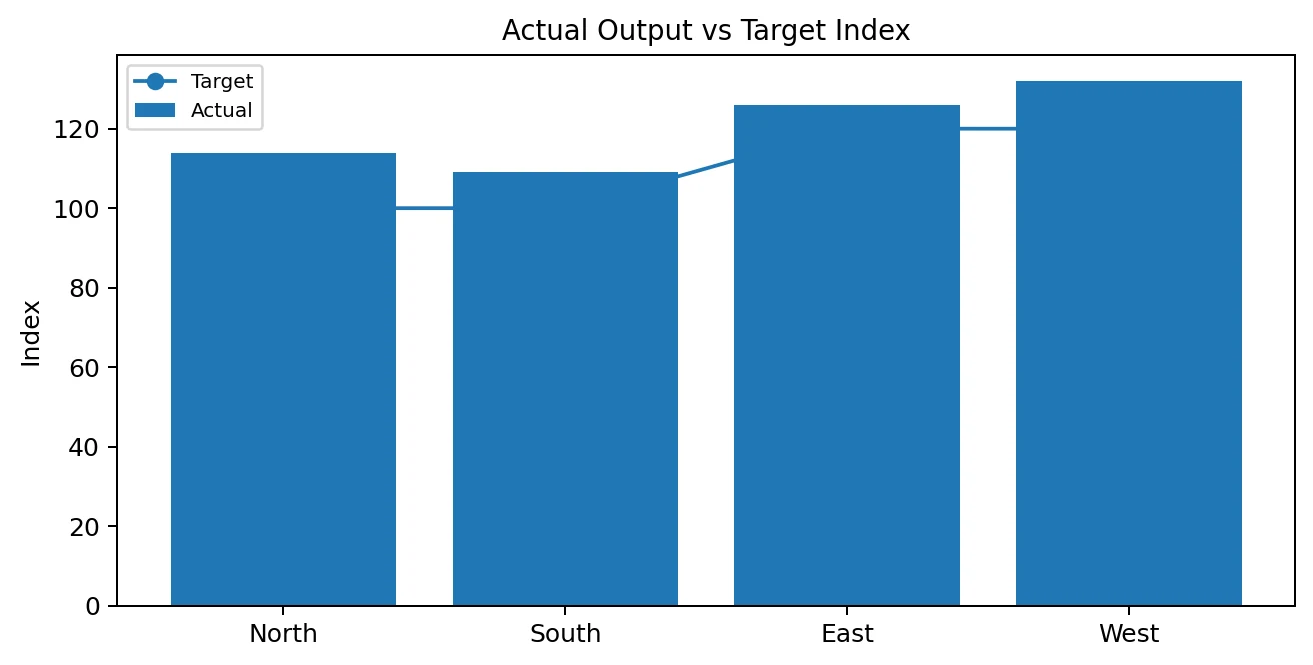
| Bonus rule | £750 for each team whose actual output is at least 110% of target |
Question. What is the total bonus pool?
| Team | Actual output | Target |
|---|---|---|
| North | 114 | 100 |
| South | 109 | 100 |
| East | 126 | 120 |
| West | 132 | 120 |
View answer & worked solution
- A team qualifies for the bonus only if actual output reaches at least 110% of target.
- North: target = 100, 110% of target = 110, actual = 114, so it qualifies.
- South: target = 100, 110% of target = 110, actual = 109, so it does not qualify.
- East: target = 120, 110% of target = 132, actual = 126, so it does not qualify.
- West: target = 120, 110% of target = 132, actual = 132, so it qualifies.
- 2 teams qualify, and each qualifying team receives £750.
- Total bonus pool = 2 × £750 = £1,500.

| Rules / Notes | |
|---|---|
| Discount rule | Fees are reduced by 50% |
Question. Under Plan C, if the deposit paid was £17,850, what is the final total after the fee discount? The total price shown already includes fees.
| Plan | Deposit share | Fee share |
|---|---|---|
| A | 20% | 5% |
| B | 25% | 4% |
| C | 15% | 6% |
| D | 30% | 3% |
View answer & worked solution
- For Plan C, the chart shows that the deposit is 15% of the total price and fees are 6% of the total price.
- If the deposit paid was £17,850, then total price before the fee discount is £17,850 ÷ 0.15 = £119,000.
- Fees before discount = 6% of £119,000 = £7,140.
- The question says fees are reduced by 50%, so discounted fees = £7,140 × 0.50 = £3,570.
- Final amount after the fee discount = £119,000 - £7,140 + £3,570 = £115,430.
Timing, Calculator and Estimation Strategy
There is no useful universal rule such as “spend exactly X seconds on every question” because SHL assessment products and employer configurations can differ. A better strategy is to control the amount of work you do for the question in front of you.
| Situation | Best response |
|---|---|
| Answer options are far apart | Estimate first; exact calculation may be unnecessary. |
| Answer options are close | Calculate carefully and delay rounding. |
| The chart is dense | Read the question first and locate only the required row, period or series. |
| The task has several rules | Write the rules in the order they must be applied. |
| You are stuck | Eliminate impossible options before starting another long calculation. |
Calculator use: SHL candidate support says that a calculator may be used for a numerical or calculation test unless the candidate has been instructed otherwise. Some specific assessments can provide their own embedded calculator or different instructions, so the invitation and test screen always take priority.
Before typing numbers, know the formula, the base value, the expected unit and whether the result should logically be larger or smaller than the starting value.
ReasoningCampus Numerical Difficulty Index
ReasoningCampus uses the Numerical Difficulty Index to help candidates understand why some numerical questions feel harder. This is not an official SHL score. It is a ReasoningCampus training scale for organising practice by the type and number of reasoning demands involved.
| Level | Description | Example |
|---|---|---|
| RCDI-N 1 | One direct calculation | Find 20% of 150 |
| RCDI-N 2 | One calculation with clear table data | Find sales in April |
| RCDI-N 3 | Basic percentage change | Compare Q1 and Q2 |
| RCDI-N 4 | Two-step calculation | Discount then tax |
| RCDI-N 5 | Ratio or proportion | Split total by ratio |
| RCDI-N 6 | Multi-row comparison | Compare four departments |
| RCDI-N 7 | Close answer options | Similar percentage choices |
| RCDI-N 8 | Dense data and hidden units | Multiple currencies and units |
| RCDI-N 9 | Multi-step business case | Revenue, cost, margin and growth |
| RCDI-N 10 | Timed complex reasoning | Several operations under pressure |
Move up the scale when your accuracy is stable. A harder question is useful only if it develops a new reasoning skill; repeating complex items while making the same basic error simply reinforces the error.
ReasoningCampus Error Taxonomy: Classify Every Mistake
Every wrong answer should be classified. The purpose of error review is to identify the decision that failed, not simply to record that the final option was wrong.
| Error type | What it means | Example |
|---|---|---|
| Reading Error | Misreading the question | Answering for May instead of April |
| Row Error | Using the wrong row | Using South instead of North |
| Column Error | Using the wrong column | Using revenue instead of profit |
| Unit Error | Ignoring scale | Treating thousands as millions |
| Base Error | Wrong denominator | Dividing by the new value instead of the original |
| Percentage Error | Wrong percentage logic | Confusing a 20% increase with +20 percentage points |
| Rounding Error | Rounding too early | Losing precision before the final step |
| Calculator Error | Typing the wrong number | Entering 52 instead of 5.2 |
| Logic Error | Using the wrong operation | Adding instead of dividing |
| Distractor Error | Choosing a trap answer | Selecting an intermediate result |
| Time Error | Spending too long | Over-solving a question |
| Confidence Error | Not checking | Selecting the first matching answer |
If several different questions are wrong for the same reason, the problem is no longer a single question. It is a repeatable error pattern. Use the taxonomy to decide what to practise next.
A Practical Study Plan: From Core Maths to Timed Practice
Stage 1 · Core calculations
Percentages, fractions, decimals, ratios, averages, reverse percentages and currency direction.
Stage 2 · Tables and charts
Rows, columns, totals, bar charts, line graphs, pie charts, legends and axis scales.
Stage 3 · Business calculations
Revenue, cost, profit, margins, growth, productivity, targets and thresholds.
Stage 4 · Multi-step questions
Combine two or three rules without losing the correct calculation order.
Stage 5 · Timed mixed practice
Mix question types so that you must identify the method before calculating.
Stage 6 · Error correction
Classify every mistake and repeat the question family until the error pattern stops recurring.
What ReasoningCampus Numerical Preparation Includes
ReasoningCampus numerical preparation is designed for candidates who want structured practice rather than random maths drills. Depending on the course or package, preparation can include SHL-style numerical questions, table and graph interpretation, percentage-change drills, ratios and proportions, currency conversion, profit and margin questions, timed practice, worked explanations, wrong-answer analysis, formula review, difficulty progression and mixed mock practice.
Our worked explanations focus on six practical questions: What is the task asking? Which data matters? Which formula applies? What is the shortest reliable calculation? Why is the correct answer correct? Why are the wrong options tempting?
Who Uses Numerical Reasoning Tests in Recruitment?
Numerical reasoning assessments are commonly used when a role involves interpreting data, comparing performance or making decisions from business information. Candidates may encounter them in graduate schemes, internships, finance, consulting, analyst, engineering, operations, management trainee, sales and commercial recruitment.
Numerical Reasoning Questions Candidates Often Ask
These are practical questions candidates often have before a numerical assessment. Always follow the instructions in your own invitation when they differ from general guidance.
Is SHL numerical reasoning the same as a maths test?
No. The calculations are usually practical, but the main challenge is interpreting data correctly, choosing the right relationship and working accurately under time pressure.
What maths should I revise?
Prioritise percentages, reverse percentages, ratios, averages, weighted averages, profit and margin, currency conversion, growth and chart interpretation.
Can I use a calculator?
SHL candidate support says calculators may be used for numerical or calculation tests unless the candidate is instructed otherwise. Always follow the specific assessment instructions.
Can I go back to a previous question?
Navigation can depend on the assessment. Some adaptive contexts do not allow candidates to return to previous questions, so check the instructions before starting.
What is a good SHL numerical score?
There is no single universal pass mark for every employer and every SHL assessment. Employers can use different benchmarks, roles, comparison groups and stages.
Are these real live SHL questions?
No. These are independent ReasoningCampus SHL-style training questions. They are designed to build transferable numerical reasoning skills and are not confidential live assessment items.
How This Numerical Reasoning Guide Is Prepared and Reviewed
Prepared by ReasoningCampus
This guide is published as an independent ReasoningCampus educational resource. The practice questions, worked solutions, Numerical Difficulty Index and error-review framework are ReasoningCampus training content.
Official facts checked separately
Statements about SHL assessment formats, candidate rules and product changes are checked against the official SHL sources linked below rather than inferred from third-party test-preparation websites.
Updated when the substance changes
The guide should be revised when assessment formats, official candidate guidance or the ReasoningCampus training material changes—not simply to refresh a publication date.
Editorial contact: info@reasoningcampus.com
Official SHL Sources and How We Review This Guide
This page separates official provider information from ReasoningCampus training material. Test-format and candidate-rule statements are checked against SHL's current candidate support and product information. The eight worked exercises are original independent practice content supplied for ReasoningCampus.
Independent preparation: ReasoningCampus is not affiliated with, endorsed by or sponsored by SHL. SHL is the assessment provider. ReasoningCampus provides independent educational preparation and original SHL-style practice.
Build Your SHL Numerical Reasoning Skills with Structured Practice
Use the eight examples on this page to diagnose how you read charts, choose bases and apply multi-step rules. Then move into timed topic practice and mixed mock assessments so that unfamiliar data does not change your solving process.